Quick answer: Yes. A court judgment doesn’t end the chance to negotiate. Many judgment creditors still accept less than the full balance, most often as a lump sum, because collecting the whole judgment through garnishment can take years. Get the deal in writing, pay only what the agreement says, and make sure the creditor files a satisfaction of judgment and releases any garnishment or levy.
Getting sued over a credit card or personal loan is stressful, and a judgment can feel like the end of the road. It isn’t. A judgment changes how a creditor can collect, but it doesn’t take settlement off the table. Here’s what a judgment means, what creditors can and can’t take, and how to settle one safely.
What a judgment changes
When a creditor or debt buyer wins a lawsuit, or you don’t respond in time and the court enters a default judgment, the debt becomes a court judgment. That gives the creditor tools it didn’t have before:
- Wage garnishment: an order requiring your employer to send part of each paycheck to the creditor.
- Bank levy: an order freezing and taking money in your bank account.
- Property liens: in many states, a lien on real estate you own.
- Interest and time: judgments usually earn interest and can last many years, often renewable, depending on your state.
If you’ve only been served and the deadline to respond hasn’t passed, read can a debt collector sue you first. Responding to a lawsuit is almost always better than letting a default judgment happen, and talking to a consumer attorney before the deadline is a good idea.
Why creditors still settle after a judgment
A judgment is a right to collect, not a guarantee of payment. Garnishment brings in money slowly, can stop if you change jobs, and is limited by law. Bank levies only work when there’s money in the account. For many creditors, a lump sum today is worth more than years of partial collection, which is why settlement remains common even after a judgment is entered.
Limits on what creditors can take
Wage garnishment
Under the federal Consumer Credit Protection Act, ordinary garnishment for consumer debt is limited to the lesser of 25% of your disposable earnings or the amount by which your weekly disposable earnings exceed 30 times the federal minimum wage. Many states set lower limits, and Texas, Pennsylvania, North Carolina and South Carolina largely prohibit wage garnishment for ordinary consumer debts.
Bank levies
Federal rules protect two months of federal benefits, such as Social Security and VA benefits, that are directly deposited into your account. Many states also protect a set amount of money in a bank account or allow you to claim exemptions after a levy. Deadlines to claim exemptions are short, so act quickly.
How to settle a judgment safely
- Confirm who owns the judgment. Judgments are often sold. Ask for the court case number and confirm the current owner before paying anyone.
- Know the full amount. Get a payoff figure that includes interest and court costs, so you know what you’re negotiating against.
- Make a realistic offer. Creditors usually respond best to a lump sum. If you need time to save, a short payment plan may be possible, but expect the full balance to come back if you miss a payment.
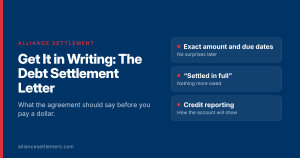
- Get it in writing first. The agreement should say the payment satisfies the judgment in full, that the creditor will file a satisfaction of judgment, and that it will release any garnishment or levy. Our guide to what a debt settlement letter should say lists the key terms.
- Pay in a traceable way and keep proof of every payment.
- Confirm the satisfaction is filed. Check the court record a few weeks later and keep a copy for your files.
What about your credit?
Civil judgments no longer appear on the three major credit reports, but the account that led to the lawsuit usually does, often as a charged-off or collection account. When it’s settled, it will typically show as settled or paid for less than the full balance. Learn more in does debt settlement hurt your credit.
When to get help
If you’re facing a lawsuit, a judgment or several collection accounts at once, it helps to have a plan for all of your unsecured debt rather than one account at a time. Alliance Settlement works with consumers carrying credit card, personal loan and medical debt, with no upfront fees. Programs typically run 12 to 48 months, and our team has been settling consumer debt since 2009. New Jersey clients are served through our partner law firm. If a lawsuit is already underway, we recommend speaking with a consumer attorney about your response deadline. Call (866) 376-2333 for a free consultation, or see debt relief options in your state.
Frequently asked questions
Can you still settle a debt after a judgment?
Yes. A judgment gives the creditor stronger collection tools, but many judgment creditors will still accept a negotiated amount, usually as a lump sum, because collecting the full judgment can take years.
What should I get in writing when I settle a judgment?
A signed agreement stating the amount accepts the judgment in full, that the creditor will file a satisfaction of judgment with the court, and that any wage garnishment or bank levy will be released.
How much of my paycheck can be garnished for credit card debt?
Under federal law, ordinary garnishment is limited to the lesser of 25% of disposable earnings or the amount by which weekly disposable earnings exceed 30 times the federal minimum wage. Some states set lower limits, and a few largely prohibit wage garnishment for consumer debts.
Can a creditor take Social Security from my bank account?
Federal rules protect two months of federal benefits, such as Social Security, that are directly deposited into your account from most bank garnishments for consumer debts.
Can debt settlement remove a judgment from my record?
Settling doesn’t erase the judgment, but once the creditor files a satisfaction of judgment, public records show it as paid. Judgments no longer appear on the three major credit reports.
This article is for general information and isn’t legal or tax advice. Garnishment and exemption rules vary by state; talk to a licensed attorney about a lawsuit or judgment.