Quick answer: Credit counseling and debt settlement are different services. A credit counselor can review your finances, help build a budget, and may offer a debt management plan that repays enrolled debts under agreed terms. A debt settlement company seeks agreements with creditors or collectors to resolve debts for less than the full balance. Neither option fits everyone, and each has costs, eligibility limits, and potential consequences.
What credit counseling may include
Credit counseling organizations commonly provide budgeting education and a review of a person’s overall financial situation. Some offer a debt management plan (DMP). Under a DMP, the client generally makes one payment to the counseling organization, which distributes payments to creditors. Depending on the creditors and plan terms, a counselor may seek lower interest rates or fees, but a DMP does not erase debts and creditors must agree to the proposed arrangement.
Ask for a written explanation of the services, setup or monthly fees, the debts included, and what happens if a creditor does not accept the plan. Confirm directly with creditors that they have accepted the proposed terms before relying on them.
What debt settlement may include
Debt settlement involves seeking an agreement with a creditor or debt collector to resolve a debt for less than the full balance. A settlement may require a lump sum or a series of payments. Creditors are not required to settle, and the amount and timing of any agreement can vary. A person may also face added interest or fees, collection activity, credit reporting effects, or a lawsuit while trying to build funds for a settlement.
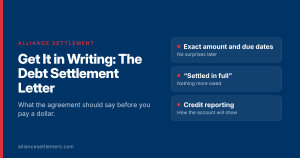
Before enrolling, ask which debts may qualify, how fees are calculated and when they are due, how any dedicated account works, what happens if a creditor refuses to settle, and how to leave the program. Read the contract carefully and get important promises in writing.
Compare the options using your own numbers
Make a list of each debt, balance, interest rate, minimum payment, current status, and due date. Then compare the total expected cost and payment schedule for each option—not just the advertised monthly payment. Include program fees, creditor payments, possible interest and late charges, and the time needed to complete the plan.
Also consider what you can realistically afford while keeping up with essential expenses. If you are receiving collection notices or court papers, do not ignore deadlines; consider getting advice from a qualified attorney. A nonprofit credit counselor may help you understand budgeting and repayment options, while a tax professional can answer questions about possible tax consequences of canceled debt.
Questions to ask before choosing
- What service will you provide, and which debts are included?
- What are all the fees, when are they charged, and what triggers each fee?
- What could happen to my credit, collection activity, or risk of a lawsuit?
- Are creditors required to accept the proposed plan or settlement?
- What happens if I cannot keep making payments or a creditor declines?
- Can I review the full agreement before enrolling?
- How can I verify the organization’s history, credentials, and complaint record?
The Consumer Financial Protection Bureau explains how credit counseling, debt management plans, and debt settlement differ. Alliance Settlement provides debt settlement services for eligible unsecured debts; that differs from a nonprofit credit counseling organization or a debt management plan. Review the program terms and risks before deciding whether to request a consultation.
Frequently asked questions
Does credit counseling settle debts for less than the balance?
Credit counseling generally focuses on budgeting and repayment. A DMP may seek changes such as lower interest or fees, but it does not erase debt. Debt settlement seeks an agreement to resolve a debt for less than the full balance, if the creditor or collector agrees.
Is a debt management plan the same as debt consolidation?
No. A DMP is a repayment arrangement coordinated through a credit counseling organization. A consolidation loan is new borrowing used to pay off other debts. The terms, eligibility, and costs differ.
Can debt settlement guarantee a specific savings amount or timeline?
No. A company cannot guarantee the amount saved or how long settlement will take. Outcomes depend on the debts, creditors, available funds, and program terms.
Can a debt settlement company charge fees before a settlement?
For debt relief services covered by the FTC’s Telemarketing Sales Rule, fees generally cannot be collected until a debt has been successfully resolved, the consumer agrees to the result, and at least one payment has been made under the agreement. Whether a particular service and transaction are covered depends on the facts. Ask for the fee terms in writing and get qualified advice if unsure. See the FTC’s explanation of the Rule’s scope and fee requirements.
This article is general information, not legal, tax, or financial advice.