
Quick answer
Prepare before you call: know your balance, what you can actually afford, and what you want to ask for, such as a lower rate, a hardship plan or a settlement. Stay calm, take notes with names and dates, and get any agreement in writing before you pay.
Facing financial difficulties is tough enough without the added stress of creditor calls. But communicating with your creditors can be a proactive and empowering step. Here’s how to handle those conversations with confidence and clarity.
1. Don’t Ignore the Problem
The worst thing you can do is avoid your creditors. Ignoring calls or letters may escalate the situation, leading to collections or lawsuits. Taking the first step to reach out shows initiative and responsibility.
2. Be Honest and Clear
Share your current financial situation honestly. Let them know what caused the hardship (job loss, medical emergency, etc.) and what you can realistically afford.
What to Say:
- “I’m currently going through financial hardship, and I’m doing my best to get back on track.”
- “I’m not able to make full payments at the moment, but I’d like to discuss a solution that works for both of us.”
3. Know Your Rights
Creditors must follow rules under the Fair Debt Collection Practices Act (FDCPA). You have the right to be treated respectfully and to request verification of any debt.
4. Request Lower Payments or Settlements
Ask if they’re open to lowering your interest rate, deferring a payment, or accepting a lump sum for less than the total owed. Many creditors prefer to settle rather than send an account to collections.
5. Keep Records
Always take notes during conversations—names, dates, amounts discussed—and ask for written confirmation of any agreement.
6. Get Help if You Need It
If you’re overwhelmed, consider working with a professional debt settlement team like Alliance Settlement. We negotiate on your behalf and help you reduce your total debt without the stress.
Frequently Asked Questions
What should I say when I call a creditor about my debt?
Explain briefly why you’re struggling, say what you can afford, and ask what hardship or payment options they offer. You don’t have to agree to anything on the first call.
Should I get a payment agreement in writing?
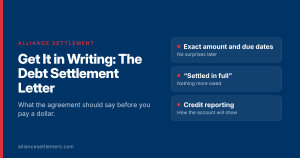
Yes. Before you send money, ask for the terms in writing, including the amount, the due dates and how the account will be reported.
Take Control of the Conversation
Speaking with creditors can feel intimidating, but the right approach can lead to real solutions. Stay calm, be prepared, and don’t be afraid to ask for help. You’re not alone on this journey.
Related reading: How Much Will Credit Card Companies Settle For? · Can a Debt Collector Sue You? What to Do If You’re Served · Debt Collector Harassment: Your Rights Under the FDCPA