How Debt Affects Your Mental Health (and What You Can Do)

Struggling with debt can lead to more than financial problems — it can affect your emotional well-being, too. Learn how debt impacts mental health and what steps you can take today to regain peace of mind and control over your future.
How Debt Affects Your Mental Health (and What You Can Do)

Quick answer

Debt can cause real stress, anxiety, poor sleep and strain on relationships, and that stress can make it harder to deal with the debt itself. Breaking the problem into steps helps: list what you owe, learn your options and talk to someone. If stress or low mood is affecting your daily life, talk to a doctor or a mental health professional as well.

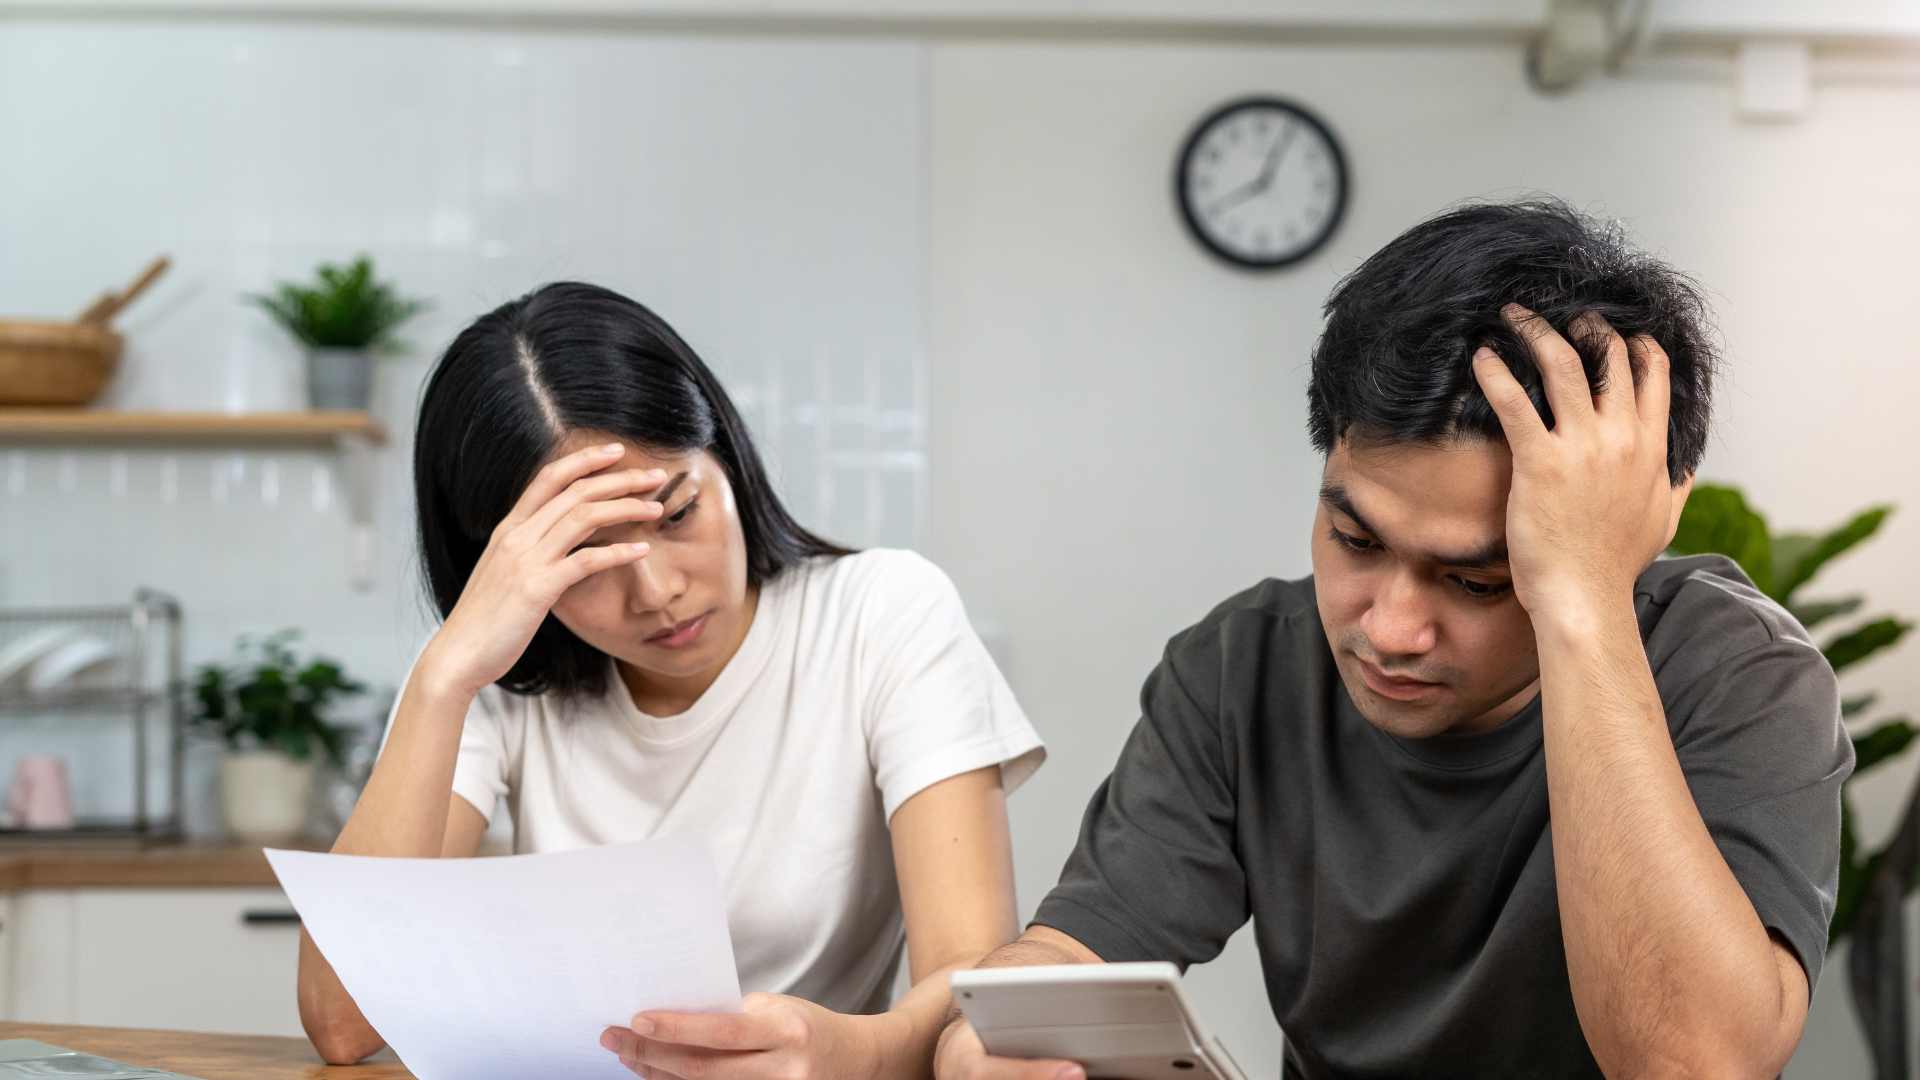
Living with debt isn't just a financial issue. It’s an emotional one too. When bills pile up and calls from collectors keep coming, the stress can take a serious toll on your well-being.

Does any of this sound familiar?

  • You feel anxious every time you check your bank account
  • You avoid opening mail because you're afraid of another bill
  • Your sleep or relationships are affected by constant money worries

These are all signs that your debt is impacting your mental health. And you're not alone. Many people face this every day.

How does debt affect your mental health?

  • Increased anxiety and depression
  • Low self-esteem or feelings of failure
  • Constant stress that can lead to burnout

Ignoring the problem won’t make it go away. But taking action can help restore your peace of mind and confidence.

So what can you do today?

  • Talk to a debt expert who can help you build a plan
  • Understand your options. You might qualify for a hardship program
  • Take the first step toward control instead of feeling stuck

You deserve to feel calm and confident about your future. Let us help you get there.

Frequently Asked Questions

Can debt cause anxiety and depression?

Debt is strongly linked to stress, anxiety and depression. If worry about money is affecting your sleep, work or relationships, it is worth talking to a doctor or counselor as well as getting help with the debt.

What is the first step when debt feels overwhelming?

Write down every debt, the balance and the monthly payment. Seeing the full picture usually makes it feel more manageable and shows which options fit.
Frequently Asked Questions

How does the debt relief program work?
We negotiate with your creditors to reduce what you owe, and you make one lower monthly program payment instead of paying each creditor separately.
Will this hurt my credit score?
While your credit may dip at first, many clients see improvements over time as they reduce debt and avoid missed payments.
How long does the process take?
Most clients complete the program in 24 to 48 months, depending on their debt amount and monthly contributions.
What kinds of debt are eligible?
We help with most unsecured debts including credit cards, medical bills, personal loans, and collections.
Are there any upfront fees?
No. We only charge fees after successfully settling your debt and you've made at least one payment towards the settlement.
Can I negotiate a debt settlement on my own?
Yes, it's possible to negotiate directly with creditors, but having professional assistance can often lead to better outcomes and less stress.
What happens if a creditor refuses to negotiate?
If a creditor is unwilling to negotiate, we explore alternative strategies, including continued negotiations or considering other debt relief options.
Will I be protected from creditor calls?
While we can't guarantee all calls will stop immediately, enrolling in our program often reduces the frequency of collection calls over time.
Is forgiven debt taxable?
In some cases, forgiven debt may be considered taxable income. We recommend consulting with a tax professional for guidance specific to your situation.
How do I know if I'm a good candidate for debt relief?
If you're struggling with unsecured debts and finding it hard to make minimum payments, our program may be a suitable solution for you.